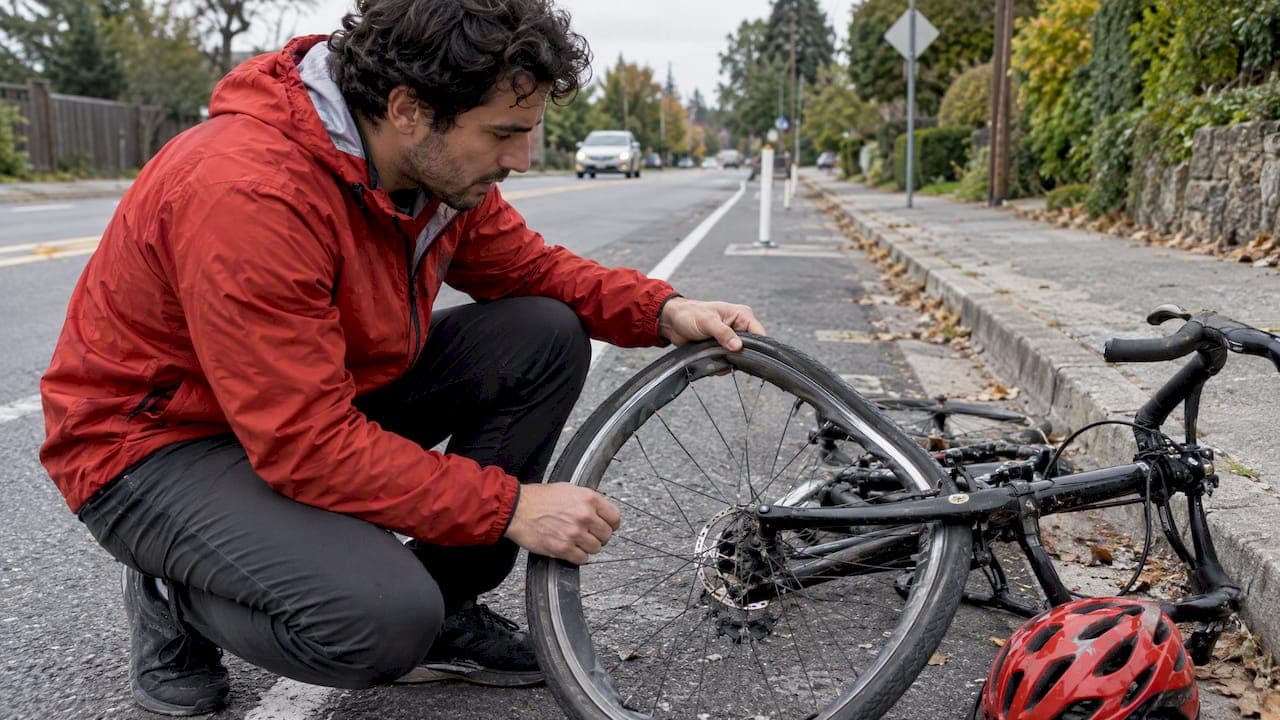
Your settlement value comes down to three things: how severe and lasting your injuries are, how well you can document your financial losses, and how much insurance money is actually available to pay you. Ranges vary enormously from case to case, so a realistic number requires looking at your specific medical records, lost income, and the at-fault party's coverage. Preserving evidence early and getting a free case evaluation can help you see where you actually stand.
TL;DR:
- Document injuries with consistent medical care, imaging, future care plans, and a symptom journal; gaps let insurers challenge causation, severity, or ongoing effects.
- Your recovery may shrink under comparative negligence rules or disappear entirely in contributory negligence states; municipal claims can require notice within 60 to 180 days.
- A driver's policy limit can cap recovery below documented losses; cyclists without auto policies should check household policies for uninsured or underinsured motorist coverage.
- Insurers often offer settlements 30 to 90 days after a crash, before treatment ends; waiting for maximum medical improvement clarifies future care and lost income.
- Attorneys may value pain and suffering by multiplying economic losses by 1.5 to 5, with more severe, lasting injuries supporting higher factors.
Table of Contents
- What Makes Up a Bicycle Accident Settlement
- How Injury Severity and Documentation Drive Value Up or Down
- What Bicycle Accident Settlements Typically Look Like
- How Fault Rules Can Reduce or Block Your Claim
- Why Insurance Coverage Sets the Real Ceiling on Your Recovery
- What to Document in the Hours and Days After a Crash
- How the Settlement Timeline and Negotiation Usually Unfold
- How Attorneys Convert Losses Into an Estimated Range
- What I Tell Clients Weighing a Free Evaluation
- Get a Free Case Evaluation for Your Bicycle Accident Claim
- FAQ
- Sources
What Makes Up a Bicycle Accident Settlement
A settlement is a sum of several distinct categories, not a single lump figure pulled from a chart. Economic damages are the easiest to calculate because they come with receipts and pay stubs attached. Non-economic damages require more judgment, and special categories apply only in specific situations.
Economic damages typically include:
- Medical bills, past and projected, including emergency care, surgery, imaging, physical therapy, and medication
- Future care costs when a doctor documents ongoing treatment, assistive devices, or additional procedures
- Lost wages for time missed from work, plus diminished earning capacity if your injury limits your job options
- Self-employment or business losses calculated from tax returns or contracts you couldn't fulfill
- Property damage covering your bicycle, helmet, phone, clothing, and any gear destroyed in the crash
Non-economic damages cover pain and suffering, emotional distress, and loss of enjoyment of life. Attorneys commonly use one of two methods to translate these into numbers. The multiplier method takes your total economic damages and multiplies them by a factor, often between 1.5 and 5, depending on injury severity. A broken wrist might justify a lower multiplier, while a spinal injury with permanent limitations pushes toward the higher end. The per-diem method instead assigns a daily dollar value for every day you experienced pain, from the crash date until maximum medical improvement.
Two special categories apply only in particular circumstances. Loss of consortium compensates a spouse or family member for the impact your injury has on your relationship and shared life. Wrongful death claims arise when a cyclist dies from crash-related injuries, and the available damages shift to cover funeral expenses, lost future income, and the surviving family's loss of companionship and guidance. Our car accident settlement factors list walks through how these categories apply across different crash types, which maps closely onto bicycle cases.
How Injury Severity and Documentation Drive Value Up or Down
Severity and documentation work together. A severe injury with thin medical records often settles for less than a moderate injury backed by a thorough paper trail, because insurers pay based on what they can verify, not on what actually happened.
Injury severity increases value primarily by driving up future-care costs. A traumatic brain injury illustrates this well. Emergency department visits for bicycle-related traumatic brain injuries numbered an estimated 596,972 between 2009 and 2018, and most of those patients were treated and released the same day. That matters for settlement purposes because a same-day release does not mean the injury was minor. Many TBI symptoms, including cognitive changes and chronic headaches, surface weeks after the crash, and a claimant who stops tracking symptoms after an ER discharge risks undervaluing a genuinely serious injury.
A 2016 Marketscan-based analysis estimated the annual healthcare cost attributable to nonfatal TBI at tens of billions of dollars nationwide(https://stacks.cdc.gov/view/cdc/105004/cdc_105004_DS1.pdf), with per-patient costs rising sharply for higher-severity cases even though low-severity TBIs contribute heavily to the total because they occur so often. That spread shows why two cyclists with the same diagnosis code can end up with very different settlement values depending on how their treatment unfolds.
Objective findings carry more weight than self-reported pain. Adjusters and juries respond to:
- Imaging results such as MRIs or CT scans showing fractures, bleeding, or soft-tissue damage
- Surgical reports documenting the procedure and expected recovery trajectory
- Physical therapy notes that track functional progress or lack of it over time
Consistent treatment matters almost as much as the injury itself. Gaps in care give insurers an argument that you either recovered faster than claimed or that something unrelated to the crash caused your ongoing symptoms. A physician's written future-care plan, specifying additional surgery, long-term therapy, or permanent restrictions, is often the single document that moves a settlement from the low end of a range to the high end.
What Bicycle Accident Settlements Typically Look Like
Settlement amounts span a wide range because no two crashes produce the same combination of injury, income loss, and available insurance. Rather than quoting one average figure, it helps to look at three rough severity bands and what tends to drive each one.
- Low severity: Road rash, bruising, or a minor fracture that heals within a few weeks, with a handful of urgent care visits and little to no missed work. Medical bills typically stay in the low thousands, and the settlement reflects those bills plus a modest pain-and-suffering amount.
- Mid severity: A fracture requiring a cast or minor surgery, several months of physical therapy, and a few weeks away from work. Medical costs climb into the tens of thousands, and lost wages become a meaningful part of the total alongside a higher multiplier for ongoing discomfort.
- High severity: A traumatic brain injury, spinal damage, or multiple fractures requiring surgery, extended rehabilitation, and possibly permanent limitations on work or daily activity. These cases can involve substantial future medical costs and lost earning capacity, pushing settlement demands well into six figures.
Even a high-severity case with strong medical documentation can settle for less than its theoretical value when the at-fault driver carries a modest insurance policy. A claim valued at $300,000 on paper may practically cap out near the driver's policy limit if no other coverage applies, which is why insurance availability matters as much as injury severity. This is also why published "average settlement" figures mislead more than they help: they blend minor road rash cases with catastrophic injury cases, producing a number that doesn't resemble either one.
How Fault Rules Can Reduce or Block Your Claim
Even a strong medical record doesn't guarantee full compensation if you share any blame for the crash. States follow different fault rules, and which one applies to your case can swing your final recovery by tens of thousands of dollars.
Three general frameworks exist across the U.S., and the specifics of negligence law vary by state, so checking your jurisdiction's exact rule matters before estimating a value:
- Pure comparative negligence lets you recover damages reduced by your fault percentage, even if you were 90% at fault
- Modified comparative negligence bars recovery once your fault reaches a threshold, commonly 50% or 51%, depending on the state
- Contributory negligence, used in a small number of states, bars recovery entirely if you bear any fault at all
Insurance adjusters routinely argue that a cyclist contributed to the crash by not wearing a helmet, riding outside a marked lane, or lacking proper lights at night. These arguments can be countered with police reports noting the driver's violations, witness statements, traffic camera footage, or an accident reconstruction showing the driver had the last clear chance to avoid the collision.
Claims against a government entity, such as a city responsible for a poorly maintained bike lane, follow different procedural rules than claims against a private driver. These often include short notice deadlines, sometimes as brief as 60 to 180 days, and damage caps that limit total recovery regardless of injury severity. Checking these rules immediately after a crash involving a public road defect or municipal vehicle is essential before assuming a standard timeline applies.
Why Insurance Coverage Sets the Real Ceiling on Your Recovery
Fault establishes who owes you money, but insurance coverage determines how much of that debt actually gets paid. A well-documented, high-value claim against a driver with minimal coverage often recovers far less than the same claim against a driver with a substantial policy.
The at-fault driver's liability policy limit usually sets the practical ceiling on what you can collect from that driver directly, regardless of how severe your injuries are or how clearly they were at fault. When that limit falls short of your actual damages, uninsured and underinsured motorist coverage, known as UM/UIM, becomes the next place to look. This coverage can reimburse medical bills and lost wages when the at-fault driver carries no insurance, insufficient insurance, or flees the scene, and UM/UIM guidance from the Insurance Information Institute notes that it's mandatory in some states and varies significantly elsewhere. A cyclist without an auto policy of their own may still have access to UM/UIM through a household member's auto policy, which is a detail many injured cyclists overlook entirely. Our partners at an independent insurance agency explain UM/UIM coverage in more detail if you want to understand what your own policy or a family member's policy might offer.
Once a settlement arrives, the amount you actually keep is often smaller than the headline number. Medical liens and insurance subrogation claims allow your health insurer or medical providers to recover what they paid for your treatment directly from your settlement, before you see a dollar of it. Our guide on medical liens and net recovery breaks down how this process typically works.

Pro Tip: Ask every insurer involved, including your own auto and health policies, for a declarations page early on, so you know every potential source of recovery before you negotiate.
What to Document in the Hours and Days After a Crash
The evidence you gather in the immediate aftermath often determines whether your claim gets taken seriously or questioned at every turn. A short, deliberate checklist in the moment can protect thousands of dollars in value later.
- Photograph the scene from multiple angles, including road conditions, skid marks, your bicycle, your injuries, and the other vehicle's position and damage.
- Collect driver and witness information, including the driver's insurance details, license plate, and contact information for anyone who saw the crash happen.
- Request the police report and confirm it accurately reflects the crash, correcting any errors as soon as possible.
- Follow through on all recommended medical care, even if symptoms seem to fade, and keep every billing statement and prescription record.
- Start a recovery journal noting pain levels, missed activities, and how the injury affects daily life, which becomes useful evidence for non-economic damages later.
Avoid giving a recorded statement to the at-fault driver's insurance company before speaking with an attorney, and never sign a medical release or settlement document without understanding exactly what it waives. Our evidence best practices guide covers additional steps that apply directly to bicycle crashes.
Pro Tip: Keep a written log of every call with an insurance adjuster, including the date, the representative's name, and what was discussed, in case their account later differs from yours.
How the Settlement Timeline and Negotiation Usually Unfold
Insurance adjusters often extend a first offer within 30 to 90 days of the crash, and that offer typically arrives before your treatment is finished. Accepting early usually means settling for less, since the full scope of your medical needs and lost income isn't yet documented.
- Waiting until you reach maximum medical improvement gives your attorney a complete picture of future care costs before any number gets finalized
- Accepting an early offer resolves the claim quickly but risks leaving money on the table if complications or additional treatment emerge later
- Filing suit becomes an option when negotiations stall, though most cases still settle before trial once both sides see the full evidence record
Before any net recovery is calculated, outstanding medical liens and bills typically get resolved from the settlement proceeds, which is why the number you're offered and the amount you ultimately receive can differ meaningfully. Our breakdown of how bicycle accident cases get settled walks through this process in more detail.
How Attorneys Convert Losses Into an Estimated Range
Turning your losses into a realistic settlement estimate follows a consistent method, even though the inputs differ for every case.
- Compile verified economic damages, totaling medical bills to date, projected future care from a physician's written plan, lost wages, and property damage.
- Select a non-economic valuation approach, justifying a multiplier or per-diem rate based on injury severity, treatment duration, and documented impact on daily life.
- Apply the provable fault percentage under your state's comparative negligence rule, then test that adjusted figure against the at-fault party's collectible insurance and any applicable UM/UIM coverage.
- Subtract expected liens and subrogation claims to arrive at a realistic net recovery, typically presented as a low, likely, and high range rather than one fixed number.
This stepwise approach is why two claims with similar injuries can still produce different settlement ranges once fault, coverage, and liens are factored in.
What I Tell Clients Weighing a Free Evaluation
A free case evaluation makes the most sense when fault is disputed, you're still receiving treatment, or your injuries might require long-term care. Have your medical bills, crash photos, and police report ready since they speed up an accurate assessment. Expect an initial offer well before your treatment timeline ends, and don't mistake it for a final number.
— Gerard
Get a Free Case Evaluation for Your Bicycle Accident Claim
Figuring out what your claim is actually worth takes more than reading settlement ranges online, since your medical records, income loss, and the available insurance in your specific crash are what ultimately set the number. A free, no-obligation case evaluation gives you a tailored intake built around bicycle injuries specifically, rather than a generic accident questionnaire, and connects you with an attorney suited to your situation.
The intake process typically asks for:
- Basic crash details, including date, location, and how the collision occurred
- Injury information, covering diagnoses, treatment received, and whether care is ongoing
- Insurance details for both your own policy and the at-fault driver's, when known
There's no cost and no commitment to submitting an evaluation, and your information is handled according to our privacy policy. If you're ready to see where your claim stands, start your free evaluation today.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What is a reasonable settlement offer?
A reasonable offer covers your documented medical bills, lost wages, and property damage, plus a fair amount for pain and suffering based on your injury's severity and duration. There's no single dollar figure that applies across all cases, since the right number depends on your specific treatment record, fault percentage, and the at-fault party's available insurance.
How much compensation for being knocked off a bike?
Compensation depends on the severity of your injuries, your medical costs, lost income, and how much insurance coverage is available from the at-fault driver. A minor road rash injury settles far differently than a fracture requiring surgery or a traumatic brain injury with ongoing care needs.
What is the hardest injury to prove?
Injuries without clear objective findings, such as mild traumatic brain injuries, soft-tissue damage, or chronic pain conditions, tend to be the hardest to document because imaging and lab tests don't always show visible damage. Consistent treatment records, specialist evaluations, and a detailed symptom journal help substantiate these harder-to-prove injuries.
How much of a $40,000 settlement will I get?
Your net recovery depends on outstanding medical liens, health insurance subrogation claims, and any attorney fees, all of which typically get resolved from the settlement before you receive the remaining balance. Two claimants with identical settlements can end up with very different take-home amounts depending on their specific liens and fee arrangements.
Sources
- Emergency Department Visits for Bicycle-Related Traumatic Brain Injuries Among Children and Adults — United States, 2009–2018
- Bicycle safety and insurance | Insurance Information Institute (III)
- Negligence — Cornell Law (Legal Information Institute)