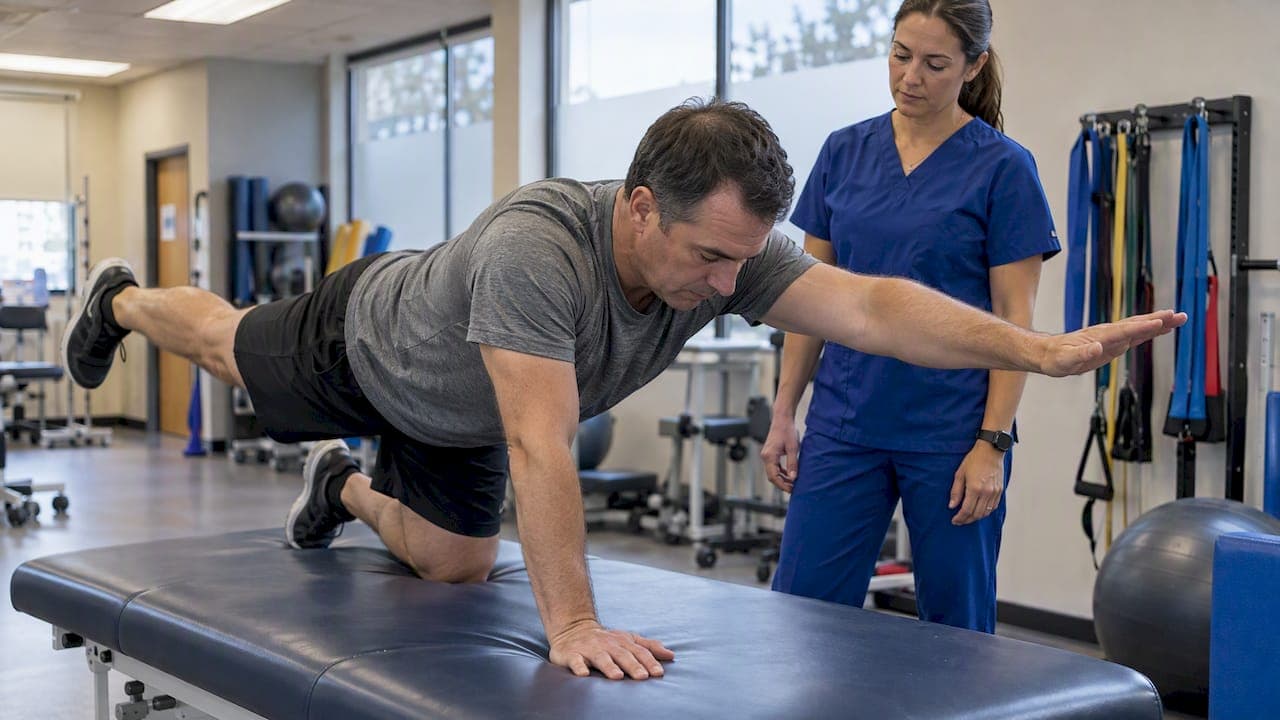
A reasonable illustrative range for a herniated disc settlement runs from a lower five-figure amount for cases treated conservatively up to a high five-figure or six-figure amount once surgery or permanent impairment enters the picture. Where your claim actually lands depends on three things: how well your imaging matches your symptoms, the size of your medical bills and lost wages, and whether you needed surgery or face lasting limitations. Insurance limits and shared fault can pull the real payout below the theoretical value, no matter how strong your file looks.
TL;DR:
- Settlement amounts vary widely based on treatment type, ranging from low five figures for conservative care to six figures for cases involving surgery or permanent impairment.
- The multiplier method for damages depends on injury severity: around 1.5 for minor strains, approximately 2.5 for moderate cases, and 4 or higher for severe ones involving surgery or nerve damage.
- Injections and surgery significantly increase settlement estimates because they add objective evidence, higher costs, and potentially permanent disability ratings.
- Timely, consistent medical treatment and clear MRI evidence matching symptoms are crucial to establishing causation and maximizing settlement potential.
- Insurance policy limits, shared fault rules, and state-specific caps often restrict actual recoveries regardless of case strength.
Table of Contents
- How settlements are calculated: economic damages and the multiplier method
- Typical settlement ranges and three illustrative examples
- Why injections and surgery change settlement value (and why that's not a strategy)
- Evidence and causation: MRI findings, timing, and the degeneration defense
- Case timeline: when claims typically settle and the tradeoffs of waiting
- Practical limits and state rules that affect what you actually collect
- How to strengthen your claim now and when to call an attorney
- Tax implications of herniated disc settlements
- If a settlement offer feels too low, here's what to do next
- Realistic expectations and the ethics of a strong claim
- Free case evaluation: a clear next step for your claim
- FAQ
- Sources
How settlements are calculated: economic damages and the multiplier method
Every herniated disc settlement starts with two categories of damages. Economic damages are the costs you can show with receipts and pay stubs: emergency room visits, physical therapy, imaging, prescriptions, and the wages you lost while you couldn't work. Non-economic damages cover pain, loss of enjoyment of life, and the disruption an injury causes to ordinary routines, and they don't come with an invoice.

To put a number on non-economic damages, insurers and many attorneys lean on the multiplier method. They add up your economic damages, then multiply that figure by a number tied to severity. A minor strain with a quick recovery might use a multiplier around 1.5. A moderate herniation with months of physical therapy and injections often lands closer to 2.5. A severe case involving surgery, permanent restrictions, or nerve damage can justify a multiplier of 4 or higher. This isn't a formula either side is bound to, it's a starting point for negotiation that both sides adjust based on evidence, venue, and how sympathetic the facts are.
Here's how the math might play out:
- A claimant with $8,000 in medical bills and $2,000 in lost wages, treated with physical therapy alone, might see a multiplier around 2, producing a rough estimate near $20,000.
- A claimant with $35,000 in bills after injections and extended therapy, using a multiplier near 3, lands closer to $105,000 before adjustments for fault or policy limits.
- A claimant who underwent fusion surgery with substantial medical bills and documented permanent impairment, using a higher multiplier, could see a pre-adjustment estimate well above typical conservative figures, though actual recovery often gets capped by available insurance coverage.
These numbers are illustrative only, not guarantees. The multiplier method gives both sides a shared language for negotiation, but adjusters routinely argue for the low end of a severity band while plaintiffs' attorneys argue for the high end. For a broader look at how this plays out across injury types, our guide to settlement factors across car accident claims breaks down the variables adjusters weigh most heavily.
Typical settlement ranges and three illustrative examples
Published settlement and verdict reporters show wide swings in herniated disc outcomes, which is why a single "average" number tends to mislead more than it informs. A handful of large surgical verdicts can pull a reported mean far above what most claimants actually see, while a cluster of minor soft-tissue cases can drag a median down. The more useful approach is to think in bands tied to treatment and permanency.
Conservatively treated cases, meaning physical therapy and pain management without injections or surgery, commonly settle in the low five figures. Cases that progress to epidural steroid injections tend to move into the upper five-figure range, since injections both document ongoing symptoms and add meaningful medical costs to the file. Surgical cases, particularly those involving fusion or disc replacement, commonly report six-figure outcomes once future care and permanent impairment are factored in.
- The conservative case: A warehouse worker injured in a rear-end collision completes 12 weeks of physical therapy, racks up $9,500 in medical bills, and misses two weeks of work. Using a 2x multiplier, the estimate lands near $23,000, consistent with the low end of the conservative band.
- The injection case: A delivery driver fails to improve with therapy alone and receives two epidural injections over four months, bringing medical bills to $28,000. A 2.5x multiplier produces an estimate around $70,000, though a 20% comparative fault finding would reduce that recovery by a corresponding share.
- The surgical case: A construction worker undergoes a single-level discectomy after conservative treatment fails, with $95,000 in past medical bills and a documented 10% permanent impairment rating. A 3.5x multiplier puts the pre-adjustment estimate near $330,000, though the final recovery may be capped by the at-fault driver's policy limits regardless of the case's theoretical value.
Why injections and surgery change settlement value (and why that's not a strategy)
Treatment for a herniated disc tends to follow a ladder. Most claims start with physical therapy and anti-inflammatory medication, move to epidural steroid injections if symptoms persist, and only reach surgery when conservative care has genuinely failed. Each rung on that ladder adds something different to your claim file.
- Physical therapy documents your initial symptoms and establishes a baseline for recovery or lack of it.
- Injections create objective evidence that conservative care wasn't enough and add measurable costs to your specials.
- Surgery generates the largest increase in value because it adds major medical bills, future care projections, and often a formal impairment rating.
Research on surgical outcomes for lumbar disc herniation found that surgery often produces faster and larger early improvements compared to nonoperative care, though outcomes between the two approaches tend to converge over time, and the duration of symptoms before treatment affects how much benefit surgery provides, according to analysis of the SPORT trial. That clinical reality matters for settlement value too: surgery increases both your documented past expenses and plausible future-care costs, which raises the economic base that any multiplier gets applied to.
That said, insurers scrutinize sudden jumps to surgery closely. A claim that moves from a single physical therapy visit straight to spinal surgery, without documented failure of conservative treatment, invites skepticism and can actually weaken your position. Surgery has to be medically necessary and clearly justified in the record, not pursued as a way to inflate a number.
Pro Tip: Follow your treating physician's recommended sequence of care exactly. Skipping steps or treatment gaps give adjusters an easy reason to argue your injury wasn't as serious as claimed.
Evidence and causation: MRI findings, timing, and the degeneration defense
Insurance adjusters don't settle generously just because you say your back hurts. They want objective proof that the accident caused or worsened a specific, identifiable injury, and MRI imaging is usually the centerpiece of that proof.
- An MRI showing a herniation that matches your reported symptoms, such as radiculopathy or pain following a specific nerve pattern, carries far more weight than imaging alone.
- Certain MRI findings, including nerve-root compression and thecal sac compression, are linked to how much benefit a patient is likely to see from surgical treatment, which research on imaging predictors has examined in detail and which can factor into how your case is valued.
- Seeking care promptly after the accident, attending appointments consistently, and getting a treating physician to state in writing that the trauma caused or aggravated your condition all strengthen the causal link adjusters are looking for.
The most common defense insurers raise is degeneration: the argument that your disc problems predate the accident and simply became symptomatic afterward. Prior imaging showing a pristine spine undercuts that defense. Gaps in treatment, on the other hand, hand the defense ammunition, since they suggest your symptoms weren't severe enough to warrant ongoing care. A clean, consistent chronology from the date of injury forward is often the single strongest asset in a herniated disc claim.
Case timeline: when claims typically settle and the tradeoffs of waiting
Maximum medical improvement, or MMI, is the point at which your doctor determines your condition has stabilized and further treatment is unlikely to produce significant improvement. Settling before reaching MMI means pricing an injury without knowing its full cost, which usually works against you.
Conservative cases, where physical therapy resolves symptoms within a few months, often settle within six to twelve months of the accident. Surgical cases, or claims where liability or causation is disputed, commonly take 12 to 24 months or longer, since attorneys typically wait until future care needs and permanent impairment are clear before finalizing a number. Our claim timeline guide walks through what to expect at each stage in more detail.

Early settlement sometimes makes sense when policy limits are low and clearly won't cover a larger claim, or when financial pressure makes waiting impractical. In those situations, factoring a reasonable estimate of future risk into the number before signing matters more than negotiating for an extra few thousand dollars.
Practical limits and state rules that affect what you actually collect
A strong case on paper doesn't guarantee a strong recovery in practice. Several real-world ceilings often matter more than the theoretical value of your injury.
- Insurance policy limits cap what the at-fault driver's insurer will pay, regardless of how high your damages run; underinsured and uninsured motorist (UM/UIM) coverage on your own policy can sometimes fill that gap through a process known as stacking.
- Most states use some form of comparative fault, where your recovery is reduced by your percentage of responsibility for the accident; a small number of jurisdictions still use contributory fault rules that can bar recovery entirely if you're found even partially at fault.
- Some states impose specific caps or procedural rules affecting certain types of damages, and tort law can shift significantly from one legislative session to the next, which is why checking your state's current rules with local counsel is worth the time before assuming any figure applies to your case.
Workers' compensation claims follow an entirely different framework than personal injury lawsuits, with state-specific formulas for disability benefits and scheduled awards. Readers dealing with an on-the-job herniated disc injury may find the workers' comp back injury calculator useful for estimating benefits under their state's specific rules.
How to strengthen your claim now and when to call an attorney
What you do in the days and weeks after an accident often matters more to your eventual settlement than anything that happens later.
- Seek medical care immediately, even if symptoms seem mild at first, since delayed treatment gives insurers room to argue the injury wasn't accident-related.
- Attend every follow-up appointment and keep copies of visit notes, imaging reports, and discharge instructions.
- Document communication with your employer about missed work, modified duties, or reduced hours.
- Photograph visible injuries, the accident scene, and vehicle damage where applicable, and save every receipt tied to medical care or related expenses.
- Avoid gaps in treatment, and follow your provider's recommended imaging and referral plan rather than stopping care once initial pain subsides.
Pro Tip: Keep a simple daily log of pain levels and physical limitations from the first week after your accident. Contemporaneous notes carry more credibility than memories reconstructed months later.
Most personal injury cases resolve through settlement after a discovery period rather than at trial, according to American Bar Association guidance on what happens after a case is filed. An attorney's main value in a herniated disc claim is building that discovery record methodically, pressuring insurers who undervalue permanent injuries, and knowing when a policy limit demand or a lawsuit makes more sense than accepting an early offer. If you're unsure whether your case needs legal representation, our overview of reasons to hire an attorney after a crash walks through the situations where it typically pays off.
Tax implications of herniated disc settlements
Most compensation for physical injuries, including herniated disc settlements, is not taxed as income at the federal level, since settlement money tied to a physical injury is generally treated as compensation for a loss rather than earnings. That principle applies to amounts covering medical bills, pain and suffering stemming from the physical injury, and most lost wages when they're part of a physical injury claim.
Exceptions exist. Any portion of a settlement allocated to punitive damages is typically taxable, and interest that accrues on a settlement before it's paid out is also usually taxable. If your settlement includes compensation for emotional distress that isn't connected to a physical injury, that portion may be treated differently than the physical injury compensation itself.
Settlement agreements sometimes break out how funds are allocated across categories like medical expenses, lost wages, and pain and suffering, and that allocation can affect how the IRS treats each piece. Because every claimant's tax situation differs based on income, state residency, and the structure of the settlement, a tax professional or accountant familiar with personal injury settlements is the right resource for case-specific guidance rather than general assumptions.
If a settlement offer feels too low, here's what to do next
A first offer from an insurance adjuster is rarely their final number, and a low offer isn't the end of negotiations. The first step is a written counteroffer that walks through your medical records, bills, and any permanent impairment findings, directly addressing whatever justification the adjuster gave for their low number.
If the adjuster won't move meaningfully, request the specific reasoning behind their valuation in writing. Adjusters sometimes undervalue claims by citing gaps in treatment or questioning causation, and having their stated reasoning in writing lets you or your attorney respond to those exact points with additional medical documentation or a treating physician's letter.
When negotiation stalls entirely, filing a lawsuit doesn't mean you're headed to trial. It opens formal discovery, which often pressures insurers to reassess their position once they see the strength of your evidence under a court timeline. If you haven't already, this is typically the point where working with an attorney shifts from optional to practical, since deadlines, procedural rules, and negotiation leverage all become more complex once a claim moves toward litigation.
Realistic expectations and the ethics of a strong claim
The most honest advice I can give anyone researching herniated disc settlements is this: pursue the care your body actually needs, not the treatment you think will look best on paper. Insurers are good at spotting a chronology built around strategy rather than medicine, and it tends to backfire.
A free evaluation can be genuinely useful here, not because it promises a number, but because it gives you a clearer sense of whether your documentation, timeline, and treatment history support the kind of claim you think you have. That clarity matters more than any guess at a settlement figure this early in the process.
— Gerard
Free case evaluation: a clear next step for your claim
Figuring out where your herniated disc claim stands doesn't require guessing at multipliers or comparing your case to strangers online. A free, no-obligation case evaluation gives you a review of your medical bills, treatment history, and the liability picture, matched to attorneys who handle spine injury claims specifically.
That targeted matching matters most in cases with complicating factors like a degeneration dispute or low insurance limits, situations where a generic estimate won't tell you much.
- A review of your medical bills and treatment timeline to date.
- An assessment of likely liability issues specific to your accident.
- Matching with attorneys experienced in spine injury claims in your state.
Before starting, gather your medical records, accident report, and any correspondence from insurance adjusters. You can begin the process anytime through our free case evaluation page.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What is the average settlement for a herniated disc?
There's no single reliable average, since outcomes vary widely based on treatment and permanency. A reasonable illustrative range runs from roughly $25,000 for conservatively treated cases to $150,000 or more for surgical cases with lasting impairment, with many claims settling somewhere between those points depending on medical bills, fault, and insurance limits.
Can you recover 100% from a herniated disc?
Many people recover full or near-full function with conservative treatment like physical therapy, especially when the herniation is caught early and symptoms are mild to moderate. Others, particularly those with nerve compression or who require surgery, may experience lasting limitations even after treatment, which is part of why documented permanency matters so much in settlement valuation.
Is a herniated disc a permanent disability?
Not always. Many herniated discs improve significantly with conservative care and don't result in permanent disability, while more severe cases involving nerve damage or failed surgery can lead to lasting impairment ratings. Whether a specific case qualifies as a permanent disability depends on medical evaluation, not the diagnosis alone.
Does a back injection increase your settlement?
Epidural steroid injections often do increase settlement value because they add documented medical costs and demonstrate that conservative treatment alone wasn't sufficient. Injection-level claims tend to settle in a higher range than cases treated with physical therapy alone, though the increase still depends on your overall medical bills and the strength of your supporting records.